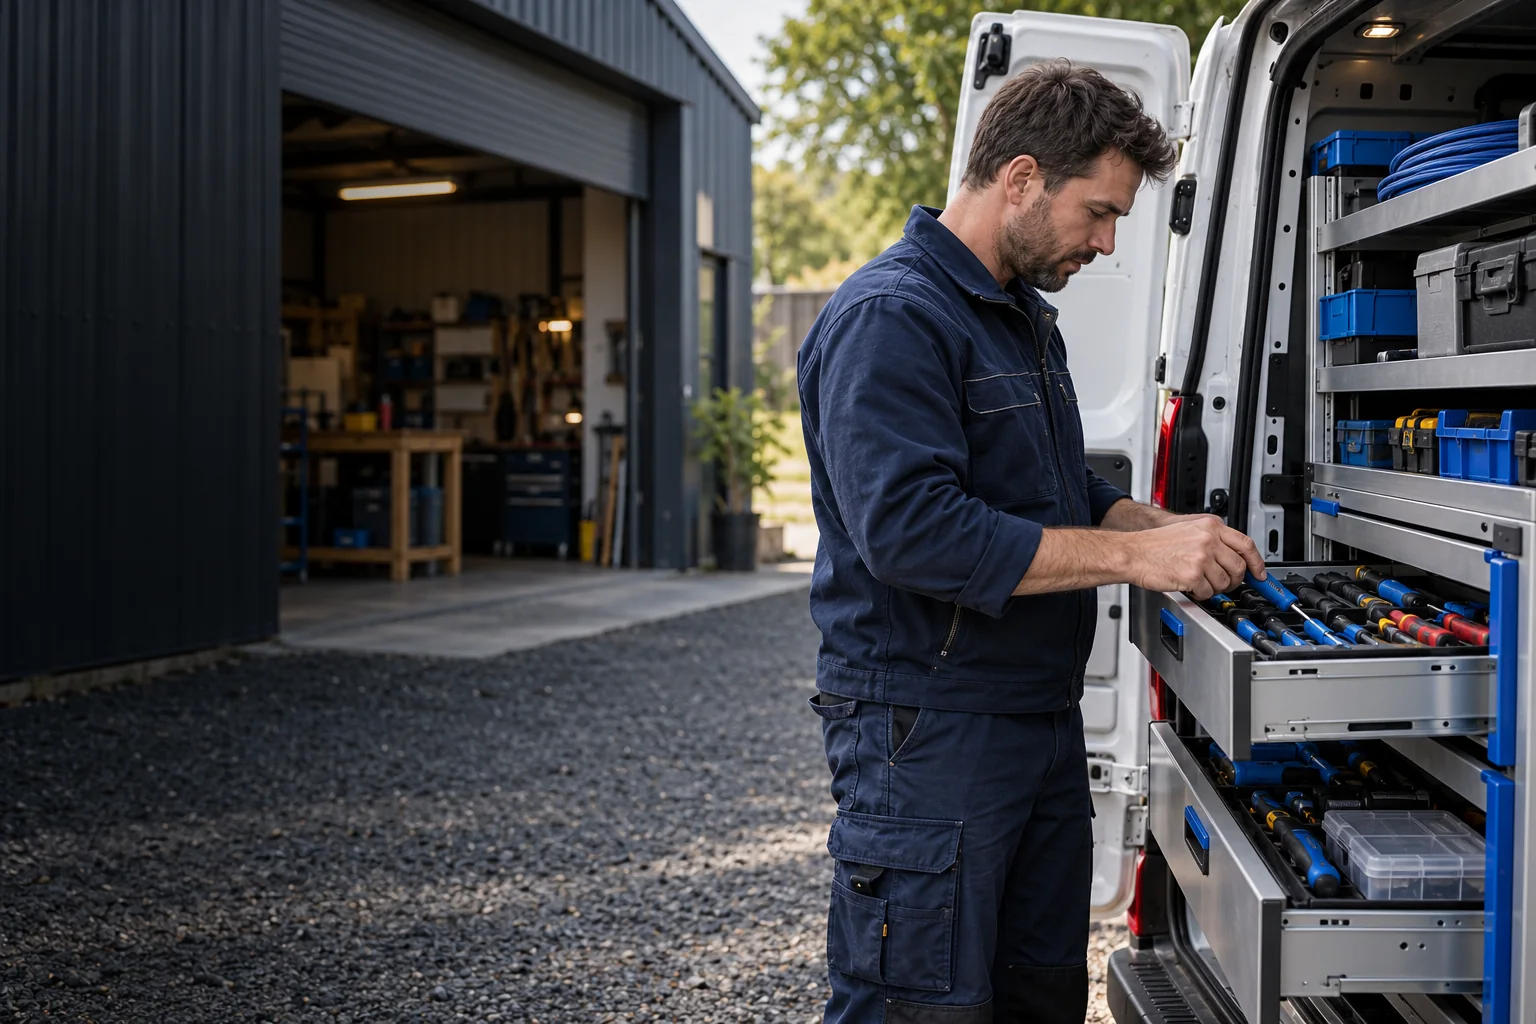
An electrical contractor needs a service van. One loan clears the balance quickly but takes a large payment every month. Another leaves more breathing room but keeps the debt around for longer. Neither option becomes suitable simply because its payment or interest rate looks smaller.
Comparing short-term vs long-term business loans means matching the borrowing to the job it funds and the cash that will repay it. Your goal is a repayment calendar you understand before you sign.
Start with the spending, not the label
Lenders do not all use the same boundary between short-term and long-term borrowing. Ask for actual payment dates, maturity and any balance due at the end. Term loans generally fund a defined amount up front and have a repayment schedule, while the available structures vary. [1]
First decide whether the money will support a short operating cycle or a longer investment. Materials for one customer job, a vehicle used for several years and an ongoing shortage of operating cash are different needs. They should not share a repayment plan just because they can all be called business expenses.
The financing options anchor guide gives the wider product map. For a repeating operating gap, also compare a working capital loan and line of credit.
Follow the cash back to the business
Write down when the financed activity should generate or preserve cash. For an order, that may be a customer's deposit and final payment. For a van, it may be several years of service work. For equipment, allow time for delivery, installation and productive use.
A longer-lived asset can create a problem if its purchase drains the cash needed to run daily operations. Financing guidance distinguishes that investment need from the cash needed between supplier payments and customer collections. [2]
Then test your expectations. A vehicle can be off the road. Installation can run late. A contract can pay more slowly than the invoice terms suggest. The repayment calendar should show those risks, rather than assuming the business receives money exactly when it plans to.
Worked example: two schedules for the same van
Assume a fictional contractor borrows $30,000 at a fixed nominal annual interest rate of 12%, calculated monthly at 1%. Compare equal end-of-month payments over 12 and 36 months. Assume no fees, no balloon payment and no other charges.
| Comparison | 12 months | 36 months |
|---|---|---|
| Principal borrowed | $30,000 | $30,000 |
| Monthly payment | About $2,665.46 | About $996.43 |
| Total scheduled payments | About $31,985.56 | About $35,871.45 |
| Interest within those payments | About $1,985.56 | About $5,871.45 |
Totals use the unrounded calculated payment. An actual schedule may adjust its final payment for rounding. These are illustrations, not available offers.
The longer schedule lowers the monthly payment by about $1,669.03 but adds about $3,885.89 of interest under these assumptions. It buys payment flexibility at a higher total cost. If the contractor has only $1,300 available each month after existing obligations, the shorter schedule does not fit that cash budget. The longer one still needs testing for quieter months and other risks.
Your next step is not to copy the example's term. It is to obtain actual schedules for your own amount and compare their cash effect.
Separate amortization from maturity
Amortization is the schedule used to spread principal repayment. Maturity is when the loan is due to end or be repaid under the agreement. They can differ.
Ask whether the proposed payments reduce the balance to zero by maturity. If not, identify the remaining balance and its intended repayment source. Do not treat a possible renewal or future refinancing as committed money.
An interest-only period also needs a second look. It postpones principal payments; it does not remove the principal. Put the later payment increase into the forecast before judging the early months affordable.
Compare the conditions beside the payment
The interest rate is only part of the comparison. Fees, payment frequency and early repayment provisions can change the total cash cost. [3]
Check these details for every offer:
- Net money available after any deductions at funding.
- Fixed or variable interest, including the basis of any variable rate.
- Daily, weekly or monthly payment dates.
- Fees, required services and third-party costs.
- Prepayment permissions and any charge for paying early.
- Security, guarantees and reporting commitments.
- The final balance and any renewal conditions.
For weekly payments, use the actual calendar. Four weekly payments are not a full typical month's payments over a year. For a variable rate, test a higher-payment scenario rather than relying only on today's figure.
Build your own repayment calendar
Complete the loan-term comparison worksheet. Record the purchase, its expected useful period, the first cash benefit, the weakest operating month and the full proposed schedule. Keep two realistic alternatives beside each other.
Use loan analysis for the cash received, fees and obligations. If you are changing existing borrowing, connect the comparison to the business debt review instead of measuring savings from the monthly payment alone.
Your main achievement is a clear trade-off: what a lower payment costs, what a faster repayment demands and which uncertainties could change the result.
Frequently asked questions
Is a short-term loan always cheaper?
No. A shorter repayment period can reduce interest when other assumptions are the same. Actual rates, fees and structures may differ, so compare the full cash flows.
Is a long-term loan always safer for cash flow?
No. Smaller payments may help, but debt can outlast the benefit it funded. A final balance, variable rate or restrictive conditions may create another risk.
Should a vehicle loan last as long as the vehicle?
The expected useful period is one input. Also consider maintenance, replacement timing, resale uncertainty, affordability and the lender's actual terms.

Choose a repayment plan the business can explain
ALOS can help you organize loan terms and compare their payment and fee effects. Bring actual schedules and a realistic cash forecast so the financing discussion starts with the business's operating needs.
ALOS supports financing preparation. Lenders make their own assessments and credit decisions. Illustrative calculations are not offers or a promise of savings.Also read
Sources and methodology
[1] Bank of America: Business financing options. U.S. educational overview of term loans and credit lines. Product and program examples are specific to their provider and jurisdiction.
[2] BDC: Techniques for better cash flow management. Canadian guidance on distinguishing longer-term asset purchases from operating cash needs.
[3] Chase: Lesser-known costs of borrowing. U.S. borrower guidance on costs and repayment considerations beyond the stated interest rate.
Sources reviewed October 22, 2026. The van example is original editorial arithmetic using standard monthly amortization. It excludes fees, taxes, insurance, maintenance, late charges and early repayment. The 12% rate is hypothetical. No universal definition of a short-term loan or recommended repayment term is assumed.